Top 10 Chemical Manufacturing Industry Suppliers Worldwide

The chemical manufacturing industry supports nearly every modern supply chain, from agricultural films and pharmaceutical ingredients to coatings, packaging, and advanced materials. Its leading suppliers operate behind familiar products, yet their influence is rarely visible to consumers. This article introduces ten major chemical manufacturers worldwide and examines why their positions matter.

Andrew Liveris, former Dow chairman and CEO, once said, “The chemical industry is the industry of industries.” That observation remains relevant. A supplier’s performance can affect factory uptime, product consistency, worker safety, and environmental reporting. A delayed resin shipment may stop a packaging line. An unstable catalyst may reduce an entire plant’s output.

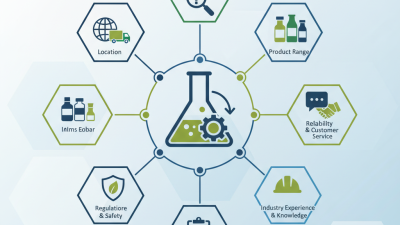
The companies discussed here are assessed through practical criteria. These include global reach, manufacturing capacity, research investment, product reliability, customer support, and progress toward lower-impact production. Public financial reports, company disclosures, industry data, and reputation also matter. No ranking is perfectly neutral.

That deserves honesty.

A large revenue figure does not guarantee dependable service. A strong sustainability claim still requires careful verification. Regional suppliers can sometimes respond faster than global giants. Smaller specialists may also provide deeper technical support for demanding applications.

The following overview is therefore a useful starting point, not a final verdict. Readers should compare certifications, delivery records, technical specifications, and local compliance requirements before choosing a supplier. In this complex market, trust is built through evidence, repeated performance, and transparent communication.

Top 10 Chemical Manufacturing Industry Suppliers Worldwide

Global Chemical Industry Scale: €5.2 Trillion in 2023 Sales and Key Regions

Global chemical manufacturing generated about €5.2 trillion in sales in 2023, according to broad industry estimates. The figure covers basic chemicals, intermediates, polymers, coatings, and specialty materials. It is enormous. Yet comparisons can mislead. Currency conversion, internal transfers, and product boundaries differ between reports. A serious supplier review must test the data source, reporting year, and regional definition before ranking capacity or reliability.

Asia-Pacific remains central to global output, supported by dense industrial clusters, large domestic markets, and expanding downstream demand. Production corridors in East and South Asia connect refineries, ports, packaging plants, and electronics factories through short shipping routes. Europe retains deep process expertise and strict efficiency standards, especially in advanced materials and industrial formulations. Energy costs remain a practical weakness. North America benefits from feedstock access, infrastructure, and integrated logistics, while investment continues in lower-carbon production.

The Middle East is strengthening its role through feedstock-based manufacturing and export terminals. Latin America contributes agricultural chemicals, mining inputs, and regional processing, although infrastructure gaps can slow delivery. For buyers comparing the top ten suppliers, scale alone is not enough. Check plant redundancy, quality records, audit access, emergency stock, and transport resilience. Clean-energy claims also deserve scrutiny unless suppliers publish measurable baselines. A cheaper contract may fail when one port closes or one reactor needs maintenance. That uncomfortable risk deserves more attention.
Ranking the Top 10: Revenue, Production Capacity, R&D, and Global Reach

A credible ranking of the top ten chemical manufacturing suppliers should begin with revenue, but revenue alone can mislead. Annual sales show commercial scale, while production capacity reveals whether a supplier can deliver consistent volumes during market shocks. The strongest candidates operate multiple plants, maintain backup feedstock routes, and publish measurable safety and quality data. A full storage tank is not proof of resilience.

Production capacity should be assessed by product category, not by total tonnage alone. A producer may manufacture millions of tonnes of basic chemicals but hold limited capacity for high-purity materials. Facility age, maintenance schedules, energy efficiency, and regional distribution also matter. These details often separate a dependable supplier from a merely large one.

Research and development adds another layer to the ranking. Leading suppliers invest in pilot plants, analytical laboratories, process automation, and technical teams that solve customer problems quickly. Patent activity can help, but practical results matter more, such as shorter production cycles or improved material consistency. Global reach should include local warehouses, regulatory knowledge, technical service, and emergency response. No ranking is flawless. Public financial reports may be comparable, while private capacity figures remain difficult to verify. A careful assessment should therefore explain its sources, update the data regularly, and acknowledge where evidence is incomplete.

The Top 10 Suppliers: BASF, Sinopec, Dow, SABIC, INEOS, and Five Peers

The worldwide chemical manufacturing market is shaped by ten influential suppliers across basic chemicals, polymers, specialty materials, and industrial gases. The group includes two established European producers, one major American manufacturer, one large Asian energy-linked supplier, and several diversified companies from the Middle East, Europe, and Asia. Their scale supports reliable output for packaging, construction, agriculture, electronics, and automotive production.

Experience matters here. Leading suppliers usually operate integrated plants, maintain regional warehouses, and use strict batch testing before shipment. They also invest in lower-emission processes, recycling systems, and digital monitoring. However, rankings are not perfect. Revenue can favor commodity producers, while innovation may be stronger among smaller specialty manufacturers. Buyers should compare audited performance, technical support, delivery records, and product consistency instead of trusting a list alone.

Tips: Check safety data, certification, plant location, and minimum order requirements before choosing a supplier. Request recent quality reports and sample testing. A low quoted price may hide freight delays or inconsistent specifications. I have found that clear communication with technical teams prevents costly reformulation later. Keep a second qualified supplier. It is practical risk control.

Global Chemical Manufacturing Market by Region, 2023

This chart presents estimated regional shares of global chemical sales in 2023. The figures are rounded industry-level percentages and exclude company-specific or brand-level data.

Source: Publicly reported 2023 global chemical industry market-share estimates compiled from international chemical industry statistics.

Portfolio Comparison: Petrochemicals, Polymers, Specialty Chemicals, and Fertilizers

A portfolio comparison of the ten leading global chemical suppliers should begin with product breadth, not revenue alone. Petrochemicals provide scale through ethylene, propylene, aromatics, and feedstock integration. The International Energy Agency identifies petrochemicals as a major source of future oil demand growth, increasing their strategic importance.

Polymers reveal a supplier’s manufacturing flexibility. Compare resin grades, recycled-content capability, regional plants, and technical support for packaging, vehicles, and construction. Specialty chemicals require a different lens. Formulation expertise, application testing, regulatory documentation, and customer collaboration often matter more than production volume. Cefic’s 2024 industry data places global chemical sales above €5 trillion in 2023, showing the sector’s enormous scope. Yet, scale does not automatically indicate innovation.

Fertilizers add exposure to agriculture, energy prices, and food security. The OECD-FAO Agricultural Outlook 2024–2033 projects continued fertilizer demand growth, although efficiency and environmental pressure will influence product selection. The strongest portfolios balance nitrogen, phosphate, potash, and lower-emission alternatives. The boundary is imperfect. Some suppliers classify intermediates differently, which can distort comparisons. Buyers should examine audited capacity, regional reliability, energy intensity, and research spending rather than accept a polished ranking. Data needs context. A large polymer portfolio may still lack specialty grades, while a smaller supplier may offer deeper technical value.

2030 Supplier Outlook: Decarbonization, Circularity, Digitalization, and Growth

Top 10 Chemical Manufacturing Industry Suppliers Worldwide
By 2030, leading chemical suppliers will compete on measurable decarbonization, not polished promises. Buyers will expect product-level carbon data, verified energy records, and credible transition plans. Suppliers with high-emission furnaces may combine electrification, renewable power, and lower-carbon feedstocks. These changes require large capital budgets and patient investment.

Circularity will move from pilot projects into daily plant operations. Facilities may recover solvents, reuse process water, and convert qualified waste into new feedstock. Digital systems will connect sensors, maintenance teams, and procurement decisions. A production manager could see abnormal steam use before it becomes a costly shutdown. Better forecasting may also reduce excess inventory and unnecessary transport.

Growth will remain important, especially in advanced materials, agriculture, construction, and healthcare applications. Yet expansion without environmental discipline will create commercial and regulatory risks. Suppliers should publish audit methods, boundary definitions, and progress against comparable baselines. Independent verification will matter more than attractive dashboards.

The path will not be tidy. Some recycling projects will deliver poor yields. Some emissions data will remain incomplete. That weakness deserves honest reporting, not concealment. Supplier evaluations should examine worker training, emergency readiness, traceability, and customer support alongside price. The strongest global partners will combine technical depth with practical delivery, while admitting where their 2030 plans still need revision.
Enquire Now